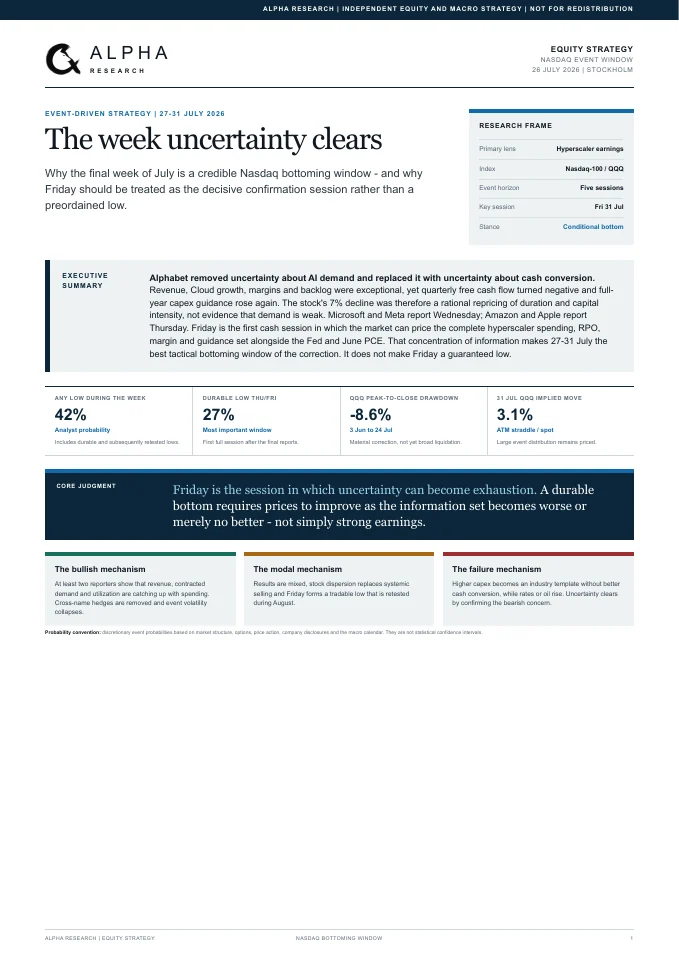
The week uncertainty clears
Why the final week of July is a credible Nasdaq bottoming window - and why Friday should be treated as the decisive confirmation session rather than a preordained low.
General research, not investment or trading advice or trade signals. Capital is at risk. Read the risks & conditions ↗
Opening the original PDF…
Original document · PDF · Scroll to read, or choose a page above.
General research, not investment or trading advice or trade signals. Capital is at risk. Read the paper’s risks and conditions before relying on the view. Holdings are those disclosed at the source date and may have changed.
Read this paper's risks & conditions ↓Report summary
The case for a tactical Nasdaq bottom during the 27–31 July earnings and macro window. Friday’s close is the confirmation test; the date alone is not enough.
The July window
The final five July sessions bring a concentrated set of earnings and macro releases. For a lasting rebound, the paper requires better cash-conversion expectations, improving breadth, lower volatility and supportive rates.
What would confirm the view
A constructive Friday close is the condition for initiating or adding tactically. It then requires QQQ to hold the event low, hyperscalers to retain their gains and revision breadth to improve. The paper does not record whether those conditions were met or a position was executed.
If confirmation fails
A mixed result favors companies with stronger cash conversion and leaves room for an August retest. Failed confirmation delays the bottom call. Scenario weights are the analyst’s judgment; monitoring levels are not recorded trade entries.
Summary sources: p. 1, p. 7, p. 8, p. 11, p. 12. Page references use the physical PDF page numbers.
Risks & conditions
Read any potential return alongside the paper's risks, conditions and limitations.
A Friday low is not enough. Confirmation requires improving cash conversion, market breadth, volatility and rates; a failed session defers the bottom call. Source: p. 7, p. 11, p. 12.
The invalidation tests include QQQ losing the event reference level without reclaiming it, a renewed volatility shock, higher Treasury yields, an oil or shipping shock, and synchronized capex increases without better economics. Source: p. 12.
Scenario probabilities are discretionary judgments. Historical prices and indicative option distributions are not executable entries, and the paper documents no confirmed fill or allocation. Source: p. 9, p. 11, p. 12.
Source record
The cover states 26 JULY 2026 | STOCKHOLM. No publication clock time or timezone is printed. Source: p. 1.
Original filename: alpha-research-nasdaq-bottom-window-july-2026.pdf
Imported:
PDF SHA-256: b761ae0e10cfac975f2a6ad0d3d1c21498eaa66085196e9be2812a9a62e0ce2d
Current assessment
No later review published.
This is the view at the paper’s source date, subject to its original conditions. It has not been reassessed here for today’s market.
Thesis history
The week uncertainty clears
The case for a tactical Nasdaq bottom during the 27–31 July earnings and macro window. Friday’s close is the confirmation test; the date alone is not enough.
Adding the paper to this library does not change its source date. Later reviews use their actual dates and link to the supporting research. Neither records a portfolio trade.
Equities research timeline
Published equities reports appear here in date order. A change in this thesis is recorded in a separate, dated assessment with the evidence behind it.
The week uncertainty clears
The case for a tactical Nasdaq bottom during the 27–31 July earnings and macro window. Friday’s close is the confirmation test; the date alone is not enough.
Framework · Conditional bottomAI Compute to 2030: Scarcity Migrates, It Does Not Disappear
Where AI compute supply could get stuck next: integration, energized sites and firm power. The question is whether usable capacity produces high-margin revenue before fixed commitments overwhelm cash generation.
Framework · Selective thematic frameworkMain Full-Risk Portfolio
A full-risk, long portfolio based on earnings conversion and valuation normalization, with position weights, valuation scenarios and the conditions that could undermine the thesis.
Deep dive · Long portfolioAI Infrastructure Is Moving From an Adoption Cycle Into a Utilization Cycle
What to watch ahead of hyperscaler earnings: agentic usage, cloud demand and whether new productive compute capacity can turn that demand into revenue and returns.
Deep dive · Positive demand thesis; conditional returnsThe original PDFs and dates are unchanged. Where a source gives only a month, reports with overlapping dates cannot be put in a definite order. A new report in this category does not confirm the thesis or record a trade.
Explore equities researchConnections between the papers
These reading links point to shared drivers or later developments, with page references to both original PDFs.
From earnings conversion to delivered compute
July separates strong cloud demand from the timing of equity cash returns. August develops the physical side of that question: usable capacity, utilization and cash gross profit must improve together. The later framework does not establish whether the July tactical bottom was confirmed.
AI Compute to 2030: Scarcity Migrates, It Does Not DisappearThis paper: p. 4, p. 7, p. 12 · Linked paper: p. 2, p. 27, p. 28, p. 29
The commodity channel into equity discount rates
July names higher yields and renewed oil disruption among the risks to the Nasdaq setup. September’s oil report examines the reverse mechanism: supply recovery could ease inflation and discount rates, provided earnings remain resilient. This is later macro context, not evidence that the July event-window conditions were met.
The Energy Peak, Refining Normalization and the Next Major Repricing in Global BondsA related paper can add context without confirming a forecast. These links and reviews do not record model-portfolio trades.