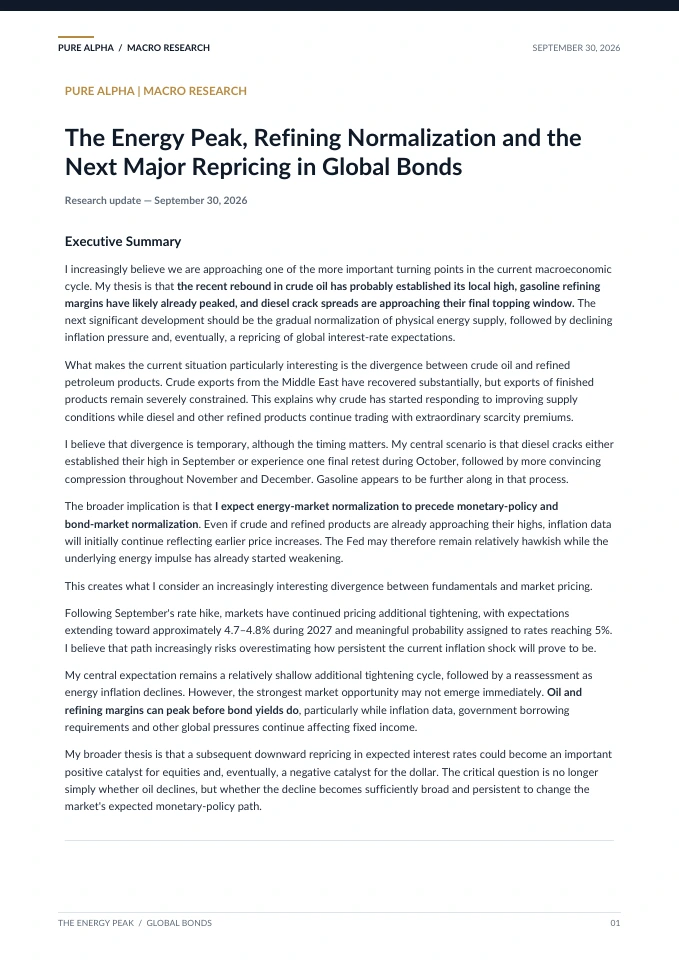
The Energy Peak, Refining Normalization and the Next Major Repricing in Global Bonds
Research update — September 30, 2026
General research, not investment or trading advice or trade signals. Capital is at risk. Read the risks & conditions ↗
Opening the original PDF…
Original document · PDF · Scroll to read, or choose a page above.
General research, not investment or trading advice or trade signals. Capital is at risk. Read the paper’s risks and conditions before relying on the view. Holdings are those disclosed at the source date and may have changed.
Read this paper's risks & conditions ↓Report summary
Recovering crude supply could ease refining scarcity and inflation, then reduce expectations for further rate hikes. The timing depends on each stage of the recovery.
Crude supply and refining margins
The paper distinguishes recovering crude supply from refined-product exports that remain constrained. Its source-date view is that gasoline margins have likely peaked. Diesel has a September–October topping window, with more convincing compression expected in November and December. Those forecasts have not been confirmed here.
The effect on inflation and rates
The proposed sequence is energy normalization, less inflation pressure, lower expected policy rates and an eventual bond-market recovery. Expected hikes can be removed before cuts begin. Longer-term yields still depend on government issuance, financing demand and international term premiums.
What that could mean for other markets
The equity case requires normalization without a material deterioration in growth or earnings. A weaker dollar also depends on relative international policy developments. The macro exposures and futures snapshots do not specify an executable instrument, entry, allocation or exit for a tracked position.
Summary sources: p. 1, p. 5, p. 6, p. 7, p. 8, p. 10, p. 12, p. 14, p. 16, p. 17, p. 18. Page references use the physical PDF page numbers.
Risks & conditions
Read any potential return alongside the paper's risks, conditions and limitations.
Renewed supply disruption, export restrictions, delayed refinery repairs, low distillate inventories and seasonal maintenance can prolong scarcity or reverse normalization. Source: p. 3, p. 4, p. 7, p. 17.
Falling energy prices may fail to improve underlying inflation. Persistent second-round effects can require further tightening and delay the expected policy repricing. Source: p. 10, p. 13, p. 17.
Fiscal borrowing, AI-related financing demand and international term premiums can keep longer-term yields elevated even if oil and headline inflation decline. Bond-market weakness can continue after energy peaks. Source: p. 11, p. 12, p. 17.
Historical timing is highly dispersed and scenario probabilities are discretionary research estimates. The $60–70 crude range for the first half of 2027 is an aggressive conditional scenario, not a guaranteed outcome or recorded trade. Source: p. 6, p. 7, p. 8, p. 17, p. 18.
Source record
Page 1 states Research update — September 30, 2026, repeated in the page headers. Page 18 states the information cutoff was September 30, before the scheduled US PCE release. No publication clock time is supplied. Source: p. 1, p. 18.
Original filename: Pure_Alpha_Research (OIL x Rates).pdf
Imported:
PDF SHA-256: b7c9cc30b02f7870ed97bc4c9f2241db014bb9300286be319f3664b90589e9eb
Current assessment
Supply adaptation strengthens; price and diesel timing remain conditional.
The October update retains September’s medium-term bearish crude thesis and expresses greater conviction in supply adaptation. Its timing confidence is more cautious: recovered exports must become sustainable inventory rebuilding before the author treats the thesis as fully confirmed. The paper favors a more persistent downside repricing in late Q4 2026 through the first half of 2027, rather than an immediate adjustment, and no longer assumes diesel cracks peak with Brent. Depleted stocks, freight costs, renewed disruption and crowded bearish positioning remain risks to the path. The assessment is unchanged overall because stronger supply conviction is offset by weaker timing confidence and a more conditional refining outlook. These are the author’s source-date interpretations, not independently verified current market conditions. The report’s references to shorts establish no actual position, transaction or allocation.
Review based on evidence through . The original paper is unchanged. This review does not record a trade.
Global Oil Market Update · p. 2, p. 5, p. 8, p. 13, p. 15, p. 16, p. 18
The 12 October update revisits supply adaptation, distinguishes export flows from inventory recovery, moderates downside timing and separates crude normalization from diesel relief. Page 18 distinguishes research positioning language from actual exposures.
Thesis history
The Energy Peak, Refining Normalization and the Next Major Repricing in Global Bonds
Recovering crude supply could ease refining scarcity and inflation, then reduce expectations for further rate hikes. The timing depends on each stage of the recovery.
Supply adaptation strengthens; price and diesel timing remain conditional.
The October update retains September’s medium-term bearish crude thesis and expresses greater conviction in supply adaptation. Its timing confidence is more cautious: recovered exports must become sustainable inventory rebuilding before the author treats the thesis as fully confirmed. The paper favors a more persistent downside repricing in late Q4 2026 through the first half of 2027, rather than an immediate adjustment, and no longer assumes diesel cracks peak with Brent. Depleted stocks, freight costs, renewed disruption and crowded bearish positioning remain risks to the path. The assessment is unchanged overall because stronger supply conviction is offset by weaker timing confidence and a more conditional refining outlook. These are the author’s source-date interpretations, not independently verified current market conditions. The report’s references to shorts establish no actual position, transaction or allocation.
UnchangedReview based on evidence through . The original paper is unchanged. This review does not record a trade.
Global Oil Market Update · p. 2, p. 5, p. 8, p. 13, p. 15, p. 16, p. 18
The 12 October update revisits supply adaptation, distinguishes export flows from inventory recovery, moderates downside timing and separates crude normalization from diesel relief. Page 18 distinguishes research positioning language from actual exposures.
Adding the paper to this library does not change its source date. Later reviews use their actual dates and link to the supporting research. Neither records a portfolio trade.
Commodities research timeline
Published commodities reports appear here in date order. A change in this thesis is recorded in a separate, dated assessment with the evidence behind it.
Gold's bear market is real; the macro turn is not yet here
The case for waiting on gold until policy expectations, ETF flows and price reactions confirm a lasting turn. Real yields remain central to the view.
Framework · Near-term downside; await confirmationThe Energy Peak, Refining Normalization and the Next Major Repricing in Global Bonds
Recovering crude supply could ease refining scarcity and inflation, then reduce expectations for further rate hikes. The timing depends on each stage of the recovery.
Update · Energy normalization; conditional rates repricingGlobal Oil Market Update
A medium-term bearish crude update: improving export flows are not yet proof of a surplus. Inventory rebuilding, freight premiums and the slower recovery in refined products determine the path lower.
Update · Bearish crude; inventory confirmation pendingThe original PDFs and dates are unchanged. Where a source gives only a month, reports with overlapping dates cannot be put in a definite order. A new report in this category does not confirm the thesis or record a trade.
Explore commodities researchConnections between the papers
These reading links point to shared drivers or later developments, with page references to both original PDFs.
Energy, inflation and the rate transmission
Gold’s July framework needs a change in real yields and investor flows, rather than one softer inflation print. September’s oil report develops a conditional path from recovering energy supply to inflation and expected policy rates, while warning that long yields can remain high. It does not provide a new gold forecast or confirm the gold turn.
Gold's bear market is real; the macro turn is not yet hereThis paper: p. 10, p. 11, p. 12, p. 17 · Linked paper: p. 3, p. 6, p. 12, p. 13
The commodity channel into equity discount rates
July names higher yields and renewed oil disruption among the risks to the Nasdaq setup. September’s oil report examines the reverse mechanism: supply recovery could ease inflation and discount rates, provided earnings remain resilient. This is later macro context, not evidence that the July event-window conditions were met.
The week uncertainty clearsLong yields connect macro conditions to the book
September’s portfolio risk map links higher real yields, wider credit spreads and weaker revisions. The later oil report explains why energy disinflation may ease policy expectations while fiscal borrowing, AI financing and term premiums keep longer yields elevated. Its equity case remains conditional on resilient growth and earnings.
Main Full-Risk PortfolioThis paper: p. 11, p. 12, p. 16, p. 17 · Linked paper: p. 19
From recovering exports to rebuilding inventories
October revisits September’s supply-adaptation and energy-normalization thesis. The author becomes more confident in improving crude availability, but less confident in immediate price normalization: durable export recovery must translate into stock rebuilding, while freight, disruption risk and refining constraints can keep prices elevated. The later paper makes the downside timing less aggressive and no longer assumes diesel cracks peak with Brent. These are evolving research views, not a verified trade or portfolio change.
Global Oil Market UpdateThis paper: p. 1, p. 2, p. 4, p. 7, p. 17 · Linked paper: p. 2, p. 5, p. 8, p. 13, p. 15, p. 16, p. 18
A related paper can add context without confirming a forecast. These links and reviews do not record model-portfolio trades.