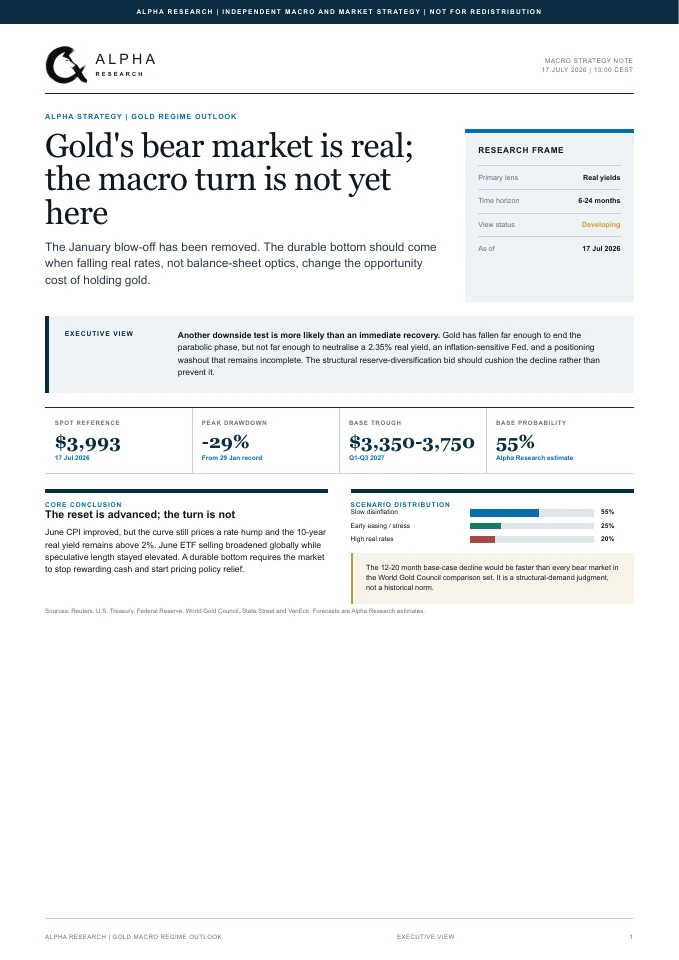
Gold's bear market is real; the macro turn is not yet here
The January blow-off has been removed. The durable bottom should come when falling real rates, not balance-sheet optics, change the opportunity cost of holding gold.
General research, not investment or trading advice or trade signals. Capital is at risk. Read the risks & conditions ↗
Opening the original PDF…
Original document · PDF · Scroll to read, or choose a page above.
General research, not investment or trading advice or trade signals. Capital is at risk. Read the paper’s risks and conditions before relying on the view. Holdings are those disclosed at the source date and may have changed.
Read this paper's risks & conditions ↓Report summary
The case for waiting on gold until policy expectations, ETF flows and price reactions confirm a lasting turn. Real yields remain central to the view.
What would confirm a turn
The report expects another downside test before a lasting recovery. It distinguishes reserve-management balance-sheet growth from monetary easing, and asks whether gold becomes more attractive relative to cash. Forecast timing and price ranges are analyst scenarios rather than observed outcomes or historical norms.
Demand and selling pressure
Official and Asian physical demand may cushion the decline, while ETF redemptions and speculative liquidation can still dominate. The confirmation tests include falling real yields, better investment flows and prices holding up to hawkish news.
The order of exposure
The paper discusses a conditional sequence: bullion first, then royalty and streaming companies, senior miners and finally juniors. GLD, IAU, GDX and GDXJ are research examples. Reference closes, security-range heuristics and scenario probabilities do not record entries or portfolio allocations.
Summary sources: p. 1, p. 2, p. 6, p. 7, p. 8, p. 9, p. 10, p. 11, p. 12, p. 13, p. 14. Page references use the physical PDF page numbers.
Risks & conditions
Read any potential return alongside the paper's risks, conditions and limitations.
Prolonged high real yields and a stronger dollar can extend the decline beyond the faster-than-historical base case. The proposed trough timing is a regime judgment, not a historical rule. Source: p. 9, p. 12.
ETF redemptions, speculative liquidation and weaker official buying can overwhelm physical demand. Structural reserve diversification does not guarantee a price floor. Source: p. 7, p. 8, p. 12.
Fiscal, geopolitical or financial stress can weaken the usual relationship with real yields and bring an earlier reversal. The paper preserves both upside and downside scenarios rather than asserting a one-way short. Source: p. 12, p. 13, p. 14.
Mining exposures add energy, wage, capital-spending, grade, jurisdiction, execution and financing risks. GDX benchmark changes affect historical comparisons; security price ranges are heuristics, not valuations or guarantees. Source: p. 11, p. 13.
Source record
The cover states 17 JULY 2026 | 13:00 CEST. Page 14 repeats the research cutoff as 17 July 2026 at 13:00 CEST. Source: p. 1, p. 14.
Original filename: alpha-research-gold-macro-regime-outlook-july-2026.pdf
Imported:
PDF SHA-256: 6c5bee49cbec79db4642b7b83514e6408300eb094cde61c5be5c87a4a8276a12
Current assessment
Energy normalization adds macro context; the gold turn remains unconfirmed.
The September oil report offers a conditional path from recovering energy supply to weaker inflation and lower expected policy rates. It also warns that fiscal borrowing, AI financing and term premiums can keep long yields elevated. This is relevant to July’s real-yield framework, but the oil paper does not establish falling real yields, improved gold flows or confirmed gold price reactions and contains no revised gold forecast. The original confirmation conditions remain the reference. This comparison does not report current market conditions or open a gold position.
Review based on evidence through . The original paper is unchanged. This review does not record a trade.
The Energy Peak, Refining Normalization and the Next Major Repricing in Global Bonds · p. 10, p. 11, p. 12, p. 17
Later energy-to-inflation-to-rates framework, with limits on the translation into real yields and gold.
Thesis history
Gold's bear market is real; the macro turn is not yet here
The case for waiting on gold until policy expectations, ETF flows and price reactions confirm a lasting turn. Real yields remain central to the view.
Energy normalization adds macro context; the gold turn remains unconfirmed.
The September oil report offers a conditional path from recovering energy supply to weaker inflation and lower expected policy rates. It also warns that fiscal borrowing, AI financing and term premiums can keep long yields elevated. This is relevant to July’s real-yield framework, but the oil paper does not establish falling real yields, improved gold flows or confirmed gold price reactions and contains no revised gold forecast. The original confirmation conditions remain the reference. This comparison does not report current market conditions or open a gold position.
UnchangedReview based on evidence through . The original paper is unchanged. This review does not record a trade.
The Energy Peak, Refining Normalization and the Next Major Repricing in Global Bonds · p. 10, p. 11, p. 12, p. 17
Later energy-to-inflation-to-rates framework, with limits on the translation into real yields and gold.
Adding the paper to this library does not change its source date. Later reviews use their actual dates and link to the supporting research. Neither records a portfolio trade.
Commodities research timeline
Published commodities reports appear here in date order. A change in this thesis is recorded in a separate, dated assessment with the evidence behind it.
Gold's bear market is real; the macro turn is not yet here
The case for waiting on gold until policy expectations, ETF flows and price reactions confirm a lasting turn. Real yields remain central to the view.
Framework · Near-term downside; await confirmationThe Energy Peak, Refining Normalization and the Next Major Repricing in Global Bonds
Recovering crude supply could ease refining scarcity and inflation, then reduce expectations for further rate hikes. The timing depends on each stage of the recovery.
Update · Energy normalization; conditional rates repricingGlobal Oil Market Update
A medium-term bearish crude update: improving export flows are not yet proof of a surplus. Inventory rebuilding, freight premiums and the slower recovery in refined products determine the path lower.
Update · Bearish crude; inventory confirmation pendingThe original PDFs and dates are unchanged. Where a source gives only a month, reports with overlapping dates cannot be put in a definite order. A new report in this category does not confirm the thesis or record a trade.
Explore commodities researchConnections between the papers
These reading links point to shared drivers or later developments, with page references to both original PDFs.
Energy, inflation and the rate transmission
Gold’s July framework needs a change in real yields and investor flows, rather than one softer inflation print. September’s oil report develops a conditional path from recovering energy supply to inflation and expected policy rates, while warning that long yields can remain high. It does not provide a new gold forecast or confirm the gold turn.
The Energy Peak, Refining Normalization and the Next Major Repricing in Global BondsThis paper: p. 3, p. 6, p. 12, p. 13 · Linked paper: p. 10, p. 11, p. 12, p. 17
Refining constraints can delay the disinflation channel
July’s gold framework distinguishes softer energy inflation from the fall in real yields and change in investor flows needed to confirm a turn. October’s oil update adds a specific limit to that transmission: crude exports can recover while diesel and finished-fuel shortages persist, delaying the broader inflation benefit. This is relevant macro context for the gold scenarios; it supplies no revised gold forecast, real-yield confirmation or gold position.
Global Oil Market UpdateThis paper: p. 3, p. 6, p. 12, p. 13 · Linked paper: p. 8, p. 13, p. 16
A related paper can add context without confirming a forecast. These links and reviews do not record model-portfolio trades.